Raporty i bazy danych
Ponad 82 publikacji obejmujących bankowość, ubezpieczenia, płatności, kredyty hipoteczne i zarządzanie aktywami w Polsce i Europie Środkowo-Wschodniej.
Zdecydowana większość naszych raportów jest dostępna wyłącznie w języku angielskim. Tytuły, opisy i spisy treści poniżej pozostają w oryginale.
Payments in Poland, 2019
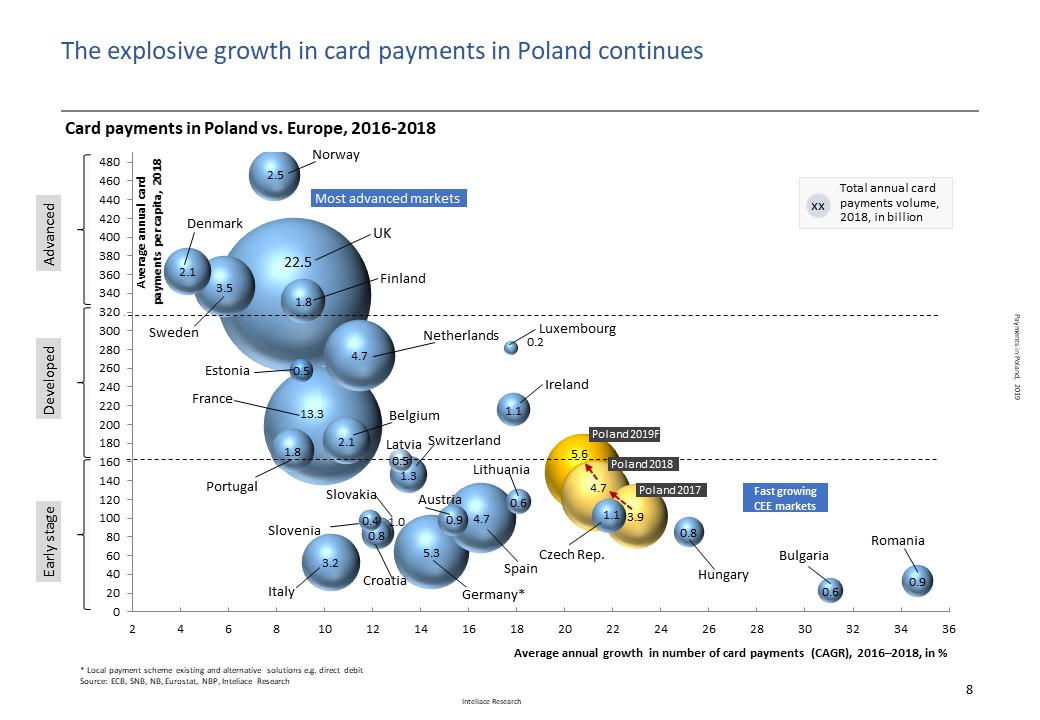
Poland's payment market continues to growth rapidly. The total number of payments exceeded 7.5 billion in 2018 and it remained on track to surpass 8.7 billion by 2019. Card payments alone reached nearly 4.7 billion transactions and they accounted for over 62% of all payments processed in the country. The persisting growth in card transactions can be attributed to fast expansion of the acceptance network and to increasing frequency in card use. In 2018, the average annual number of transactions per single card issued in Poland approached 114 tx. per card. Outlook The demand for convenient payment services and the ongoing support programs dedicated to the development of acceptance network, e.g. �Cashless Poland�, contribute to a gradual, although slow cash displacement. The current pace of growth in payment volumes is expected to remain strong, similarly to the dominating role of cards in overall payments. As a consequence, the total volume of payments in Poland is likely to reach 12 billion transactions by 2022. --------------------------------------------------------------------------------------------------------------------------------------
Investment funds and asset management market in Poland, 2019
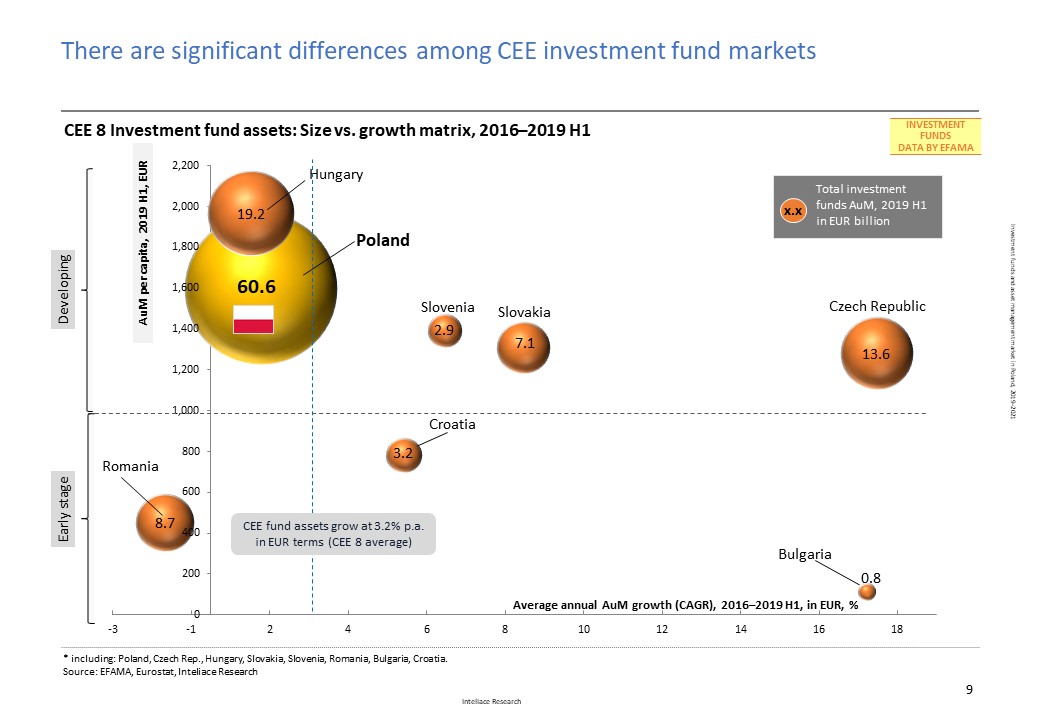
After the period of a very fast growth through 2017, total* assets under management in Poland decreased slightly to PLN 629 billion in H1 2019. The recently observed stagnation in total assets could be attributed to the weak performance of the local stock market. The recent correction affected mostly 2nd pillar pension funds, which by law have to overweight equities. Other segments remained relatively stable thanks to new contributions offsetting performance. As of June 2019, assets of regulated investment funds** reached PLN 293 billion, 3rd pillar pension assets exceeded PLN 25 billion and reserves of insurance companies remained almost unchanged at PLN 149*** billion. The asset management market remained medium-concentrated with top four groups: PZU, Aviva, NN and Ipopema managing roughly half of all assets in the market Outlook Assets under management in Poland are expected to sustain growth through 2021 while the most action is likely to take place within 3rd pillar pension funds. The new legal framework, in force since mid-2019, has mandated employers to enrol their employees and to match employee contributions. A further boost to 3rd pillar assets could be supplied by the final dismantling of 2nd pillar pension funds, although it would be initially a zero sum game or even a negative event for the sector as a whole
List of Top 200 banks in Central and Eastern Europe /2019 edition/
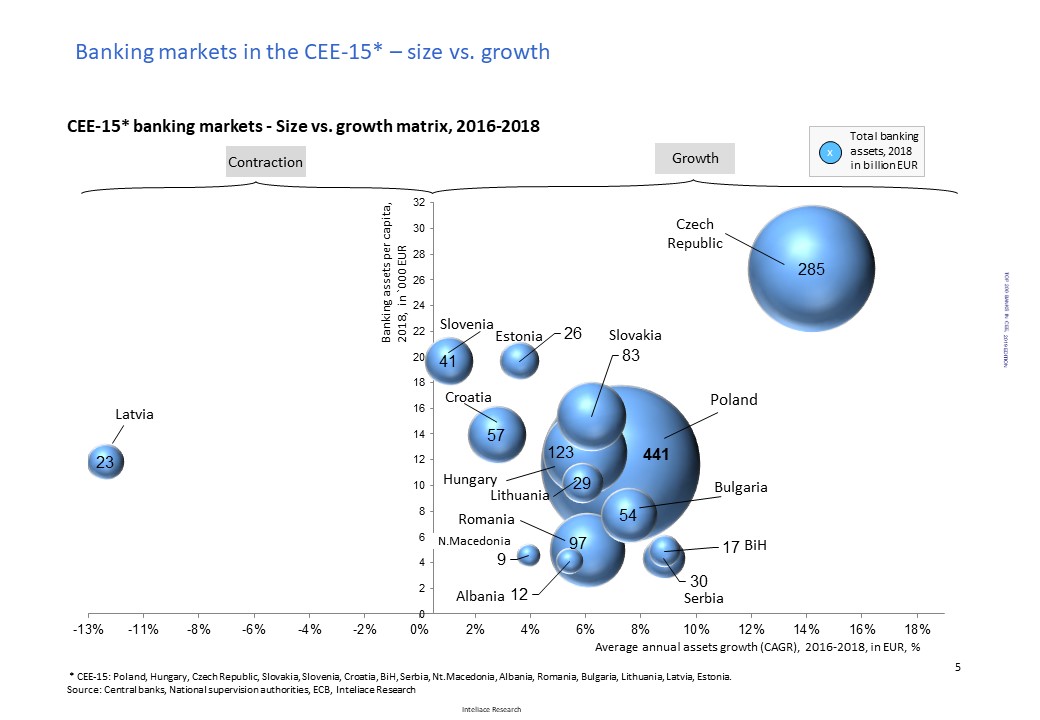
Total banking assets in CEE15* jumped to EUR 1.33 trillion in December 2018, after adding over 3.7% within last year. Markets in the Southern part of the region including Serbia, Bosnia and Bulgaria have been growing most rapidly. In a few big markets, e.g. in Poland the nominal growth in assets has been partially offset by depreciating currency. The profitability of major CEE banks improved slightly with weighted ROA and ROE improving to 1.16% and 10.4% respectively. The leading banking groups in the region: Erste, KBC and UniCredit did not change, however, the consolidation processes continued with local players getting stronger and smome foreign players reducing their presence in the region, e.g. Societe Generale or Raiffeisen. ------------------------------------------------------------------ *CEE15 include: Poland, Czech Republic, Hungary, Slovak Republic, Romania, Bulgaria, Estonia, Latvia, Lithuania, Croatia, Slovenia, Serbia, Bosnia and Herzegovina, Albania, and North Macedonia.
Insurance market in Poland, 2019-2021
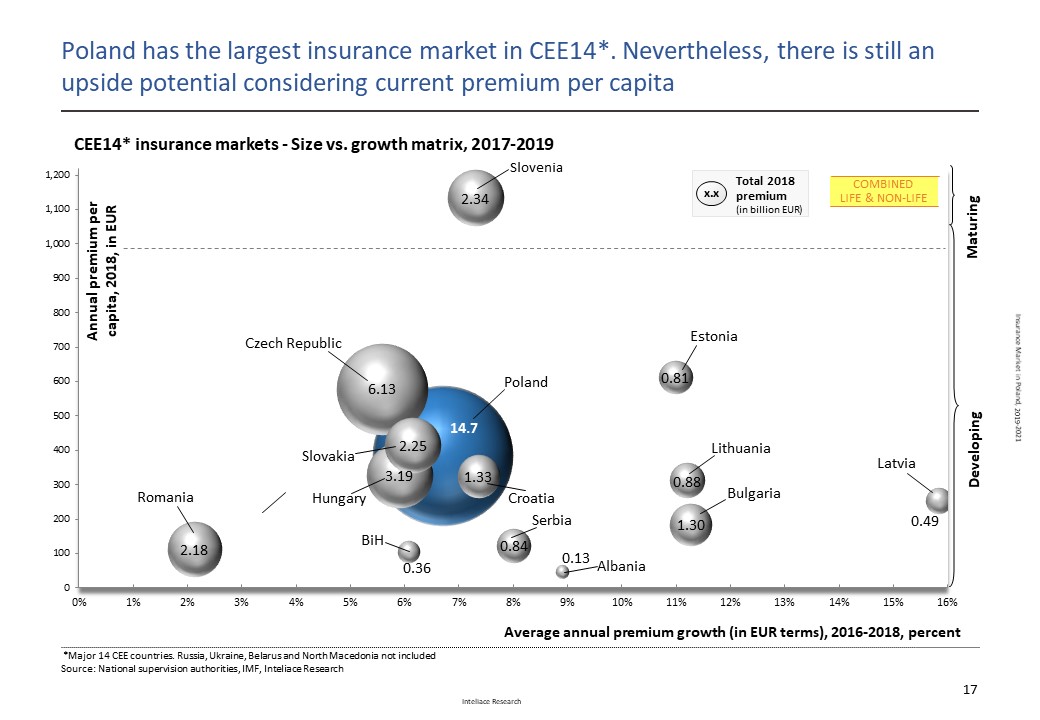
Poland has the largest insurance sector within the CEE with nearly €15 billion in premium written p.a. and almost 40% regional share in terms of GWP. There are mixed trends observed in the insurance sector in Poland recently. While the non-life segment continues with a strong growth, the life insurance segment struggles with re-adjusting of product and service offering to the new regulatory regime. Premium in the non-life segment jumped by 7% in 2018 and by 3% in 1H 2019, and it is expected to top PLN 42 billion by year end 2019. By contrast, the premium in the life segment continued to decline, falling by nearly 12% in 2018 and going down again by another 3% in 1H 2019. For more information on recent developments in the Polish insurance sector, please refer to the full publication.
Bank outlets in Poland, 2019
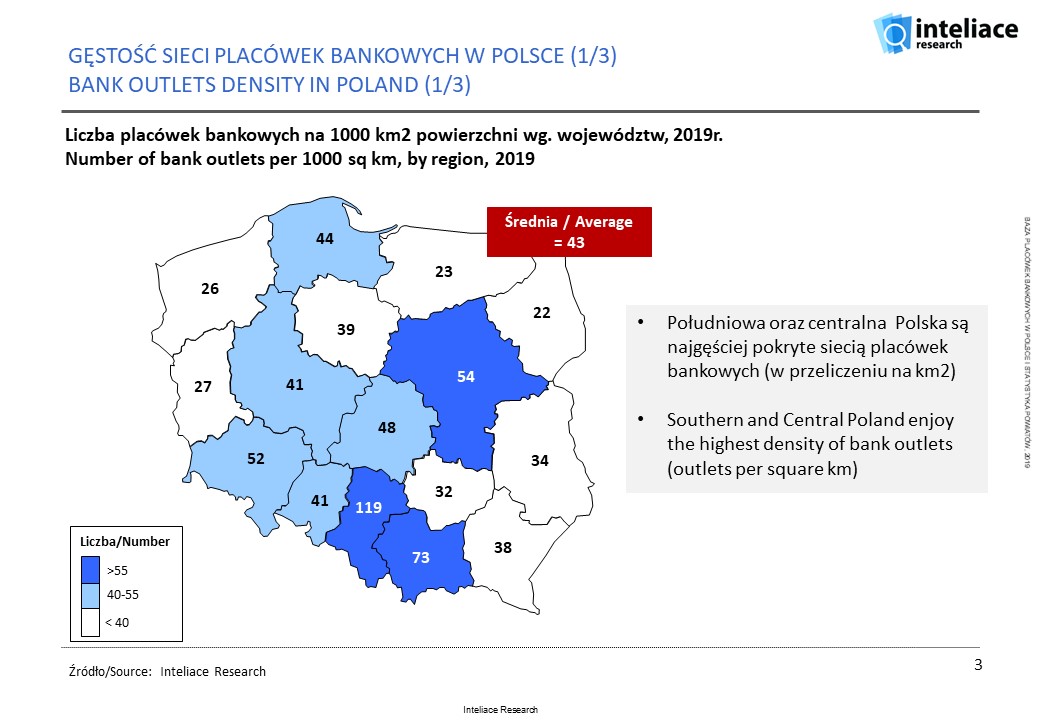
The number of bank outlets in Poland continues to fall. As of Q1 2019, there were 13412 bank and credit union outlets, which corresponded to 349 outlets per million capita. The total number of outlets fell in Q1 2019 vs. Q1 2018 by 746 outlets or by over 5% YoY. Looking forward, further bank outlet closures should be expected. An increasing use of remote channels, including mobile, and a growing personal service cost will put pressure on banks to close even more outlets. For more information please refer to the full publication/database.
Mortgage lending in Poland, 2019-2021
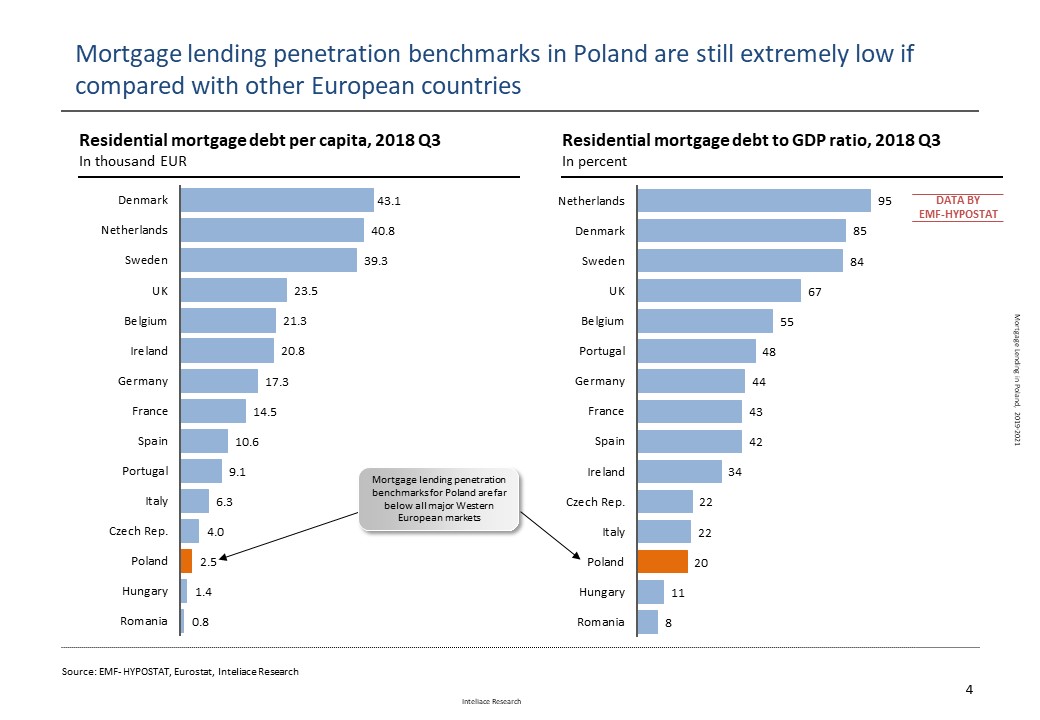
Residential construction in Poland accelerated again in 2018 extending growth trends observed since 2014. The number of completions jumped by 9%, the number of new permits increased by 3% and the number of starts surged by 19% in 2018. The key driving forces of new residential construction remained unchanged. Stable interest rates, rising purchasing power of individuals and positive consumer sentiment fuel new purchases. Moreover, real estate investments are increasingly popular in view of growing residential rents and due to low opportunity cost of holding cash or deposits. Mortgage lending accelerated in 2018. Sales of new mortgage loans increased by 11% and 20% in terms of volume and value respectively, while the average loan ticket size increased by 9%. Looking forward, in our base scenario, we expect new mortgage lending to keep growing steadily through 2021. The total outstanding is likely to increase by 6% p.a. For more information on recent developments in the Polish banking sector, please refer to the full publication.
Bank challengers in Europe 2019, company profiles
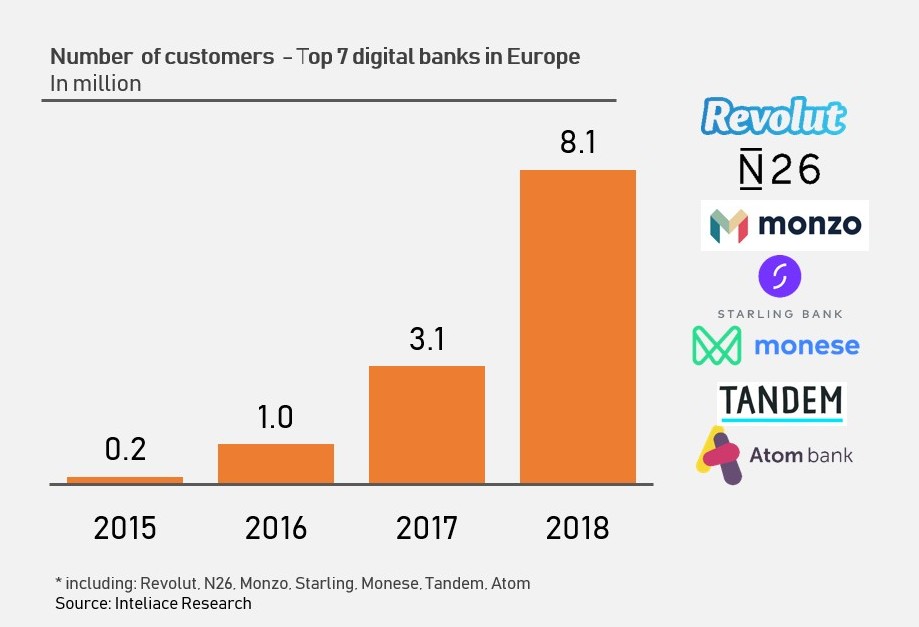
Digital banks, challenger banks, neo-banks, bank challengers in Europe A brief look at challenger banks & fintech companies in Europe reveals an exceptional growth in their customer base during last few years. While the total number of customers for the sample of 7 key players was just 0.2 million in 2015, it surged to over 8 million in 2018. --------------------------------------------------------------------------------------------------------------------------------------
Payment apps and systems in Europe 2019, company profiles
Payments Payment / P2P apps and payment systemsUser engagement is highly correlated with adoption rates. So far, only three apps managed to break the vicious cycle of low adoption & low engagement - MobilePay (Denmark), Vipps (Norway) and Swish (Sweden). --------------------------------------------------------------------------------------------------------------------------------------