About this report
Poland has the largest insurance sector in CEE14 (Central and Eastern Europe*) with nearly € 14.3 billion in premium written p.a. and a 38 % share in the region. In 2021, premium is expected to continue its growth, and to add at least 7% and 6% in non-life and in life segment respectively. A few last years have been challenging for insurers in Poland not only because of pandemics and lockdowns, but mostly due to record-low interest rates impacting gains on investments combined with rising operating costs and also considering unfavourable regulatory developments in life insurance segment. All those circumstances combined led to the falling profitability of insurers. In 2020, the net profit of non-life insurers went down by 15% to PLN 3.9 billion while the same benchmark for life insurers dropped 14% to PLN 2.2 billion. Market fragmentation and regulatory requirements result in ongoing market consolidation. After the withdrawal of AXA - acquired by Uniqa and Aegon - to be purchased by VIG, even larger deals were announced last year, e.g. Aviva to be taken over by Allianz and MetLife to be sold to Nationale Nederlanden. The outlook for insures operating in Poland remains positive. The life insurance segment is expected to continue the rebound after a long period of declines caused by the regulatory overhaul. The non-life segment is likely to benefit from the recent appreciation of value of properties, which is caused by accelerating inflation but also by increasing value of insured assets and overall growth in the wealth of individuals. For more information on recent developments in the Polish insurance sector, please refer to the full publication.
Table of contents
More on insurance
See all →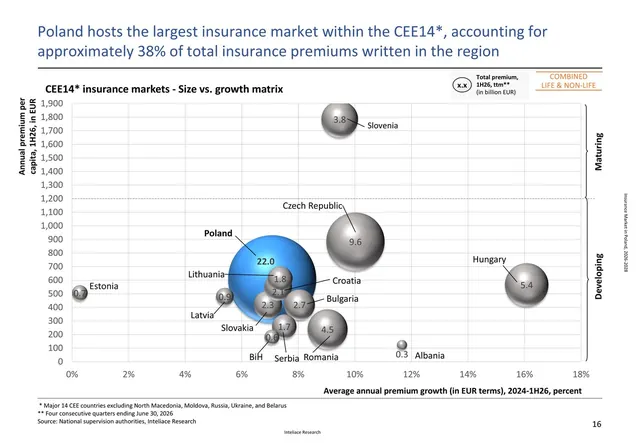
Insurance market in Poland, 2026-2028
Poland's insurance market has delivered a record year, according to the latest edition of Inteliace Research's annual analysis. Insurers wrote more than PLN 90 billion of gross premium in 2025, nearly PLN 66 billion in non-life and almost PLN 25 billion in life, and growth continued into 2026: premiums in the first half rose 7.1% year on year to PLN 47.3 billion.
Insurance market in Poland, 2025-2027
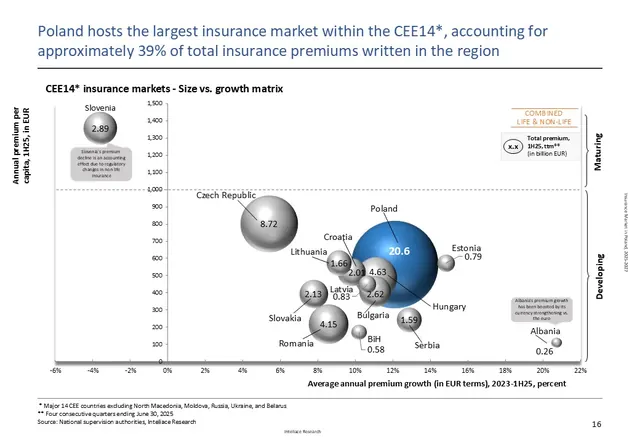
Poland's insurance market continues to demonstrate exceptional resilience and growth potential, according to the latest comprehensive analysis from Inteliace Research. Despite broader economic uncertainties, the sector is capitalizing on the country's position as one of the EU's fastest-growing economies, with total insurance premiums estimated to surpass PLN 90 billion (€21 billion) by end-2025. The Polish economy's remarkable 2.9% GDP growth in 2024, with projections accelerating to 3.2-3.6% in 2025, provides a solid foundation for insurance sector expansion. Recovering consumption patterns, moderating inflation now at 2.9%, and rising wage levels are creating favorable conditions for both life and non-life insurance growth. Market dynamics reveal interesting competitive shifts. While PZU maintains its dominant position with 44% and 27% market share in life and non-life segments respectively, mid-tier competitors like Warta (Talanx) are gaining ground through organic growth strategies, notably surpassing PZU in the large motor TPL segment. The non-life segment continues outperforming expectations, projected to reach PLN 66 billion (€15.5 billion), significantly outpacing the life segment at PLN 24.5 billion (€5.7 billion). Digital transformation is reshaping distribution channels, with price comparison platforms expanding rapidly and providing enhanced consumer choice while intensifying competition. Corporate agents and multi-agents now account for the largest sales volume portion, while direct insurer distribution gradually declines in importance. Looking ahead, the medium-term outlook through 2027 remains highly favorable. Strong private consumption, investment activity, and wealth accumulation support new premium growth, with combined life and non-life premiums forecast to exceed PLN 103 billion (€24+ billion) by 2027. Poland's commanding 39% share of the Central and Eastern Europe insurance market, valued at ~€53 billion, underscores its regional significance. For more information on recent developments in the Polish insurance sector, please refer to the full publication.
Insurance market in Poland, 2024-2026
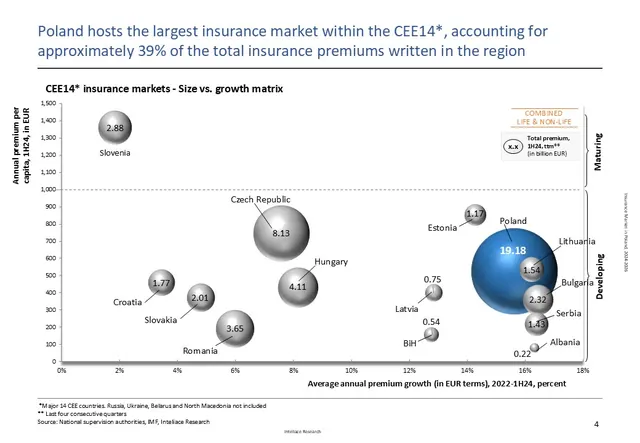
As of H1 2024, Poland, with nearly €19.2 billion in gross written premiums (GWP), accounted for approximately 39% of the total regional premium in Central and Eastern Europe. (CEE14*) Poland’s insurance sector experienced solid premium growth in 2023, with these trends continuing through the first half of 2024. The non-life segment performed particularly well, with premiums increasing by 12% year-on-year in H1 2024. In the life insurance segment, growth was lower but still significant, with premiums rising nearly 5% on an annual basis. Consistent with long-term trends, a small number of top insurers continue to expand their market share, while the collective share of smaller players is declining. This trend is likely driven by recent mergers and acquisitions (M&A) and the economies of scale enabling larger insurers to offer more competitive rates. The mid-term outlook for premium income remains positive. Projections suggest that from 2024 to 2026, the nominal growth of gross written premium (GWP) will remain stable, albeit slightly below historical averages, at approximately 8% for the non-life segment and 5% for the life segment. By 2026, combined life and non-life insurance premiums are expected to exceed PLN 98 billion (EUR 23+ billion). For more information on recent developments in the Polish insurance sector, please refer to the full publication.